
Asset Protection Law Firm Since 1991
Cook Islands Trust Attorney
Jon Alper and Gideon Alper are Cook Islands trust attorneys. They form Cook Islands trusts for clients throughout the United States and work directly with licensed trustee companies. Jon Alper is a nationally recognized expert in asset protection law and has been advising clients for over thirty-five years. Gideon Alper leads the offshore practice and previously served in the IRS Office of Chief Counsel.
Submit the form or call (407) 444-0404 to schedule a free consultation. We’ll discuss the advantages and drawbacks of a Cook Islands trust and whether one makes sense for your situation.
Our legal fee is $15,000. Consultations are by phone or Zoom, nationwide. We respond to every inquiry within one business day.
A Cook Islands trust is one of the strongest asset protection tools available. It is administered by an independent trustee company in the Cook Islands, outside the direct authority of U.S. courts.
A U.S. court can issue orders against a U.S. person, but not a Cook Islands trustee company or trust assets that have been moved offshore. That distinction sets a Cook Islands trust apart from a domestic asset protection trust.
Trustee companies are licensed and regulated by the Cook Islands Financial Supervisory Commission. They carry professional indemnity insurance and their accounts are audited annually. As a matter of the trustee company’s own policy, an attorney on its staff approves every withdrawal after verifying the request with you. Cook Islands law does not require that step.

How a Cook Islands Trust Is Structured
What a Cook Islands Trust Attorney Does
A Cook Islands trust attorney drafts the trust agreement, coordinates application and due diligence with a licensed Cook Islands trustee company, and advises on how to fund the trust. We arrange the offshore LLC and bank or brokerage account the trust often holds, plan the funding, and explain the U.S. tax reporting that comes with the trust. Jon Alper and Gideon Alper are members of the Florida Bar, and Gideon Alper is also admitted before the United States Tax Court.
How We Set Up a Cook Islands Trust
- Consultation. We talk by phone or Zoom about what you own, who your creditors are or could be, and whether a Cook Islands trust is the right tool. We look at domestic options first, and if the trust is not the right fit, we say so. If someone already has a claim against you, we still go over what can be done.
- Trustee due diligence. We recommend a licensed Cook Islands trustee company and help you gather the documents it needs: identification, a bank reference letter, proof of address, records showing where the funds came from, and an affidavit of solvency.
- Drafting. We draft the trust agreement. If the trust will hold an offshore LLC, we draft the LLC documents too.
- Signing and registration. You sign the trust agreement, and the trustee company registers the trust in the Cook Islands.
- Funding. The trustee company opens the offshore bank or brokerage account, and you transfer the assets. How long that takes depends on the account you choose.
- After funding. The trustee company administers the trust, and your accountant prepares the U.S. tax forms.
Cost and Attorney Fees
The legal fee is paid in two parts: $5,000 to start, with the rest paid after trustee due diligence.
The legal fee is flat and covers the work described above. Most clients do not need ongoing legal services after formation, and we do not charge an annual legal fee.
We have no financial interest in any trustee company or bank. Our only revenue is the legal fee paid by the client.
About Our Firm
Alper Law has helped clients nationwide with asset protection planning since 1991. Our role is to evaluate whether a Cook Islands trust fits your situation, explain the tradeoffs, and coordinate the plan if offshore planning makes sense.
Who Should Consider an Offshore Trust
An offshore trust is best suited for clients with meaningful assets and real creditor exposure. It makes sense when domestic exemptions, insurance, and LLCs no longer cover the risk. Most clients have at least $1 million in total assets or at least $500,000 in liquid assets.
A pending legal claim or existing judgment does not automatically rule out offshore planning.
Common client situations
- Business owners and entrepreneurs
- Physicians and high-liability professionals
- Real estate investors and guarantors
- Families with concentrated assets
- Clients facing serious creditor risk, including existing disputes where planning remains legally available
When a Cook Islands trust is not appropriate
- The cost is disproportionate to the assets protected
- Domestic planning already provides enough protection
- The client wants to conceal assets or avoid legal obligations
- The goal is to reduce tax liability
- The client expects the trust to eliminate all court risk
Questions About Offshore Trust Planning
Can a Cook Islands trust be used after a lawsuit starts?
Yes. Post-claim planning is still possible even after a lawsuit is filed or a judgment is entered. Liquid assets are the strong case; real estate inside the United States is harder to protect after a claim exists, because a U.S. court controls the property directly. A trust set up at that stage includes a Jones clause, which lets the trustee pay the identified creditor on defined terms and gives the settlor a defense if a court demands repatriation.
How much does the trust cost?
The legal fee is $15,000 for a Cook Islands trust or $20,000 for a Cook Islands trust paired with an offshore LLC. The Cook Islands trustee charges about $5,000 per year. The first year runs about $6,000 because it includes trust formation and opening your offshore account.
Is the trust a tax shelter?
No. A Cook Islands trust is designed for creditor protection. U.S. clients must report trust assets and income under applicable U.S. tax and information-reporting rules.
Do I have to give up control of my assets?
The trust is administered by an independent Cook Islands trustee company. When there is no legal threat, you can withdraw money by asking the trustee company, which verifies the request with you before approving it. When creditor pressure arises, the trustee can refuse to distribute assets.
How long does it take to set up?
A Cook Islands trust takes three to four weeks to establish, at which point it is signed and registered. Funding takes longer and varies with the accounts you choose. A Cook Islands bank account adds roughly three to four weeks, and a Swiss account six to eight weeks.
Who acts as the trustee?
The trustee is a Cook Islands trustee company licensed by the Cook Islands Financial Supervisory Commission. We work with several licensed trustees and recommend the one best suited to the client’s situation. We do not receive referral fees, commissions, or compensation from any trustee company.
What annual tax reporting is required?
A U.S. settlor files Form 3520 each year and is responsible for seeing that the trustee files Form 3520-A, the trust’s own return. The settlor also reports foreign financial accounts on the FBAR (FinCEN Form 114) and files Form 8938 when applicable. The client’s CPA prepares these filings, and the trustee signs the 3520-A. The trust does not change federal income tax liability. All income flows through to the settlor’s personal return as a grantor trust.
What happens if a U.S. court orders me to repatriate the assets?
The Cook Islands trustee operates under Cook Islands law and is not bound by U.S. court orders. The trust deed includes a duress clause that activates when the settlor is compelled to demand repatriation, and the trustee disregards instructions given under duress. The settlor must disclose the trust honestly to the U.S. court. A U.S. court can still hold the settlor in contempt for not producing the assets, and where the settlor genuinely cannot compel the trustee, that is the defense to contempt.
Our Attorneys
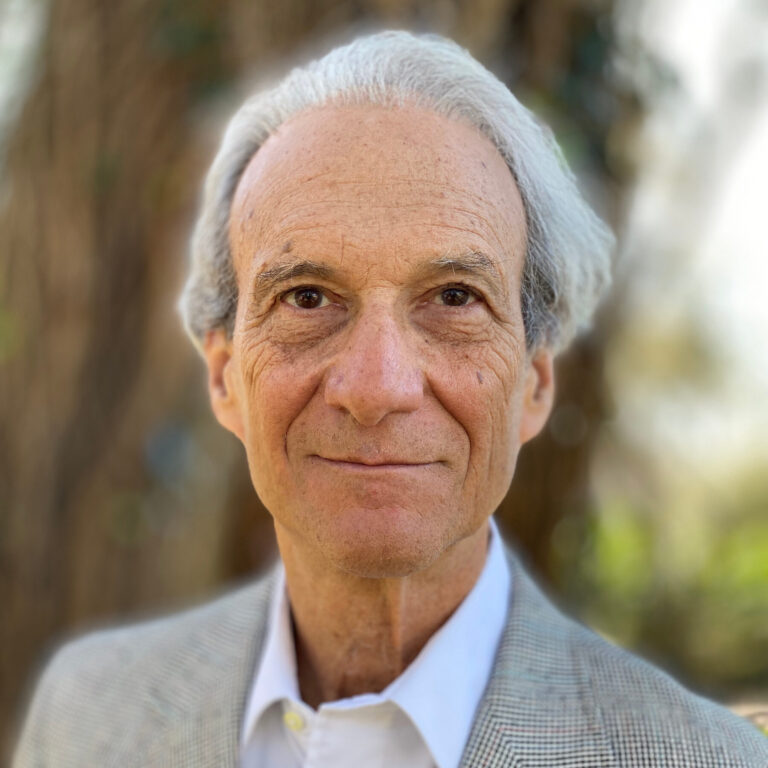
Jon Alper
Founding PartnerJon Alper has focused on asset protection planning for more than three decades. His work includes domestic and offshore planning for business owners, professionals, and families seeking creditor protection. His planning was at the heart of BankFirst v. UBS Paine Webber, Inc., the foundational Florida decision on attorney-assisted asset protection planning.

Gideon Alper
PartnerGideon Alper leads the firm’s offshore planning practice. He is a former attorney with the IRS Office of Chief Counsel in the Large Business and International Division. He advises clients on Cook Islands trusts, offshore LLCs, asset protection planning, and IRS compliance.