Florida Homestead Exemption

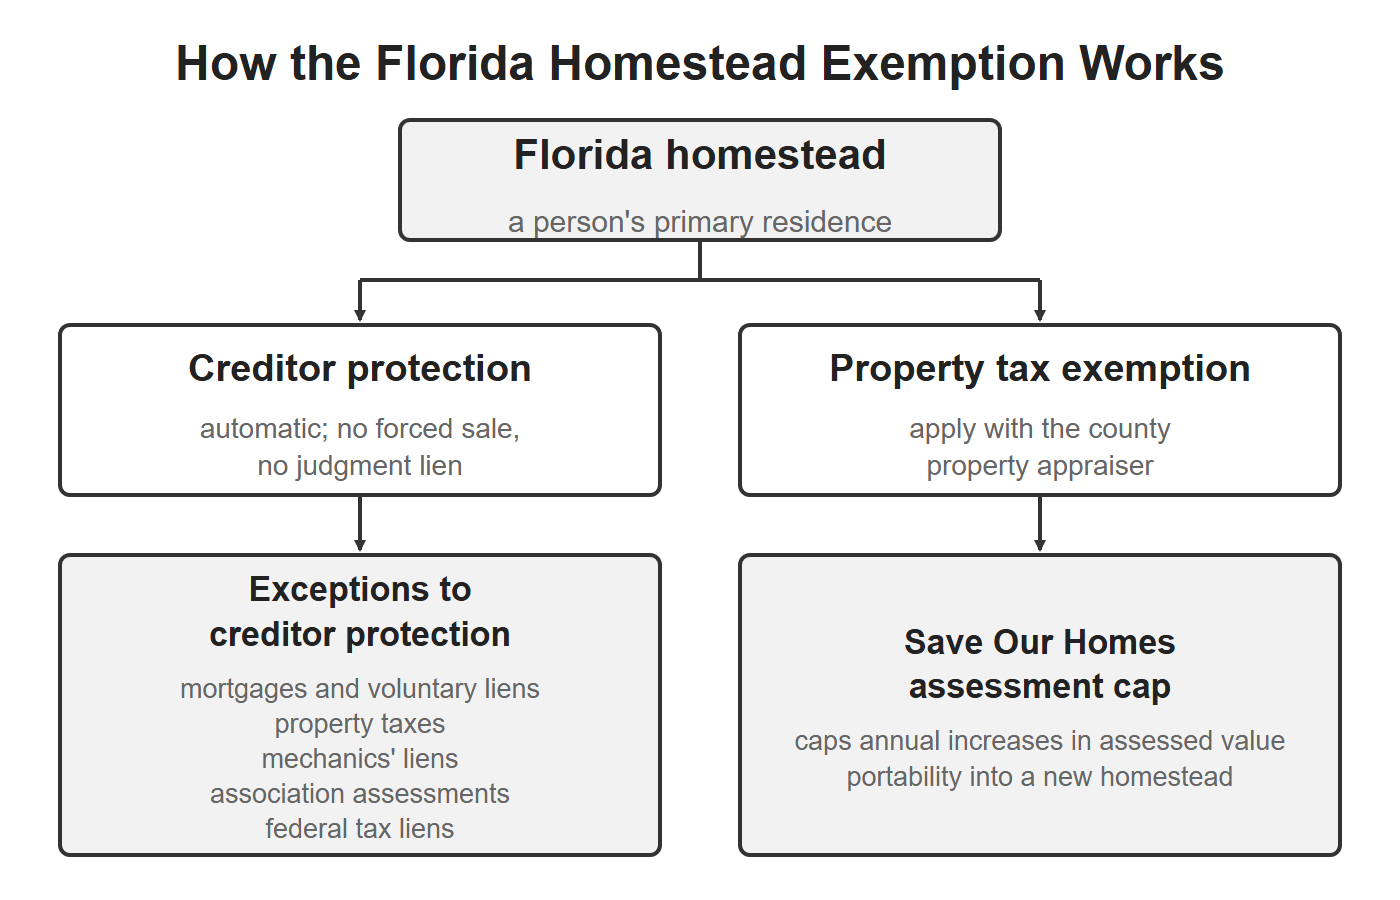
The Florida homestead exemption is a constitutional law that protects a person’s primary residence from creditors. It also reduces the home’s taxable value and caps annual increases in its assessed value.
The creditor protection is automatic, requires no filing, and has no dollar limit. The tax exemption requires an application with the county property appraiser and removes a fixed amount of the home’s assessed value from taxation.
How Does the Homestead Exemption Work?
The Florida homestead exemption has two separate parts. The first stops a judgment creditor from forcing a sale of the home, whatever its value. The second removes part of the home’s assessed value from the property tax roll and caps how fast the rest can rise. Both parts are constitutional, so changing either one requires approval by 60% of voters.
Creditor Protection
The Florida Constitution prevents a judgment creditor from forcing the sale of a Florida homestead, no matter how much the home is worth. A recorded civil judgment does not attach to or become a lien on homestead property. The protection is automatic: no application, no filing, and no waiting period.
The creditor protection appears in Article X, Section 4 of the Florida Constitution. Because the protection is constitutional rather than statutory, the legislature cannot narrow it, and courts cannot create new exceptions to it. Florida courts interpret the homestead protection generously, in the homeowner’s favor. Florida and Texas are the two best-known states that protect an unlimited amount of home equity.
A Florida resident can convert unprotected assets into homestead equity at any time, even while intending to shelter those assets from an existing judgment. In Havoco of America v. Hill, the Florida Supreme Court held that a homestead acquired with non-exempt funds stays exempt, even when the debtor intended to hinder creditors. The constitutional protection overrides Florida’s fraudulent transfer statutes. Funds traceable to fraud or egregious conduct are the exception. Courts still impose equitable liens where such funds bought or improved the homestead, or paid off a mortgage on it.
Converting legitimately earned money into a homestead is protected regardless of timing or motive. That rule applies in state court. A bankruptcy filing brings federal limits on a recent conversion. Buying a Florida homestead is often the single most effective asset protection step available to a Florida resident facing a claim.
Property Tax Exemption
The homestead tax exemption lowers the taxable value of a Florida primary residence. The first $25,000 of assessed value is exempt from all property taxes, including school district taxes. A second exemption removes another $26,411 of assessed value above $50,000 from non-school taxes in 2026. Following a 2024 constitutional amendment, the second exemption now adjusts annually for inflation. The combined exemption is $51,411 for the 2026 tax year.
The dollar savings depend on the local millage rate, because the exemption removes as much as $51,411 of assessed value from the 2026 tax base (the second $26,411 does not apply to school taxes). Claiming the exemption also qualifies the home for the Save Our Homes assessment cap, which compounds into far greater savings over time.
The Save Our Homes amendment caps the annual increase in a homestead’s assessed value at 3% or the Consumer Price Index, whichever is less. Over time, the assessed value falls further and further behind the market value. A home purchased for $300,000 that appreciates to $600,000 over 15 years might carry an assessed value of only $400,000 under the cap. The tax savings compound each year the owner holds the property.
The cap resets when the property changes ownership. An heir or buyer who takes title usually starts over at the current market value, which can cause a large jump in property taxes.
Florida also lets a homestead owner carry up to $500,000 of accumulated Save Our Homes benefit into a new homestead purchased within the state, a transfer called portability. The owner must establish the new homestead within three years and file a separate portability application (Form DR-501T) along with the new homestead application. The portability benefit reduces the new property’s assessed value, preserving years of accumulated tax savings.
Speak With Our Attorneys
Alper Law has helped clients protect their assets since 1991. Consultations are confidential, by phone or Zoom, and usually available within one business day.
Book a Consultation
Requirements
A Florida homestead is any dwelling the owner occupies as a primary, permanent residence. Courts have applied the protection to single-family houses, condominiums, co-op apartments, manufactured homes, stationary houseboats, and even recreational vehicles used as a permanent dwelling.
The constitutional protection covers homes built on owned land, while mobile homes, RVs, and alternative dwellings on leased lots fall under a separate statutory exemption in § 222.05.
A property qualifies for homestead creditor protection in Florida when three requirements are met: the owner intends it as a permanent residence, the owner actually lives there, and title is held by an individual.
1. Intent to Make the Home a Permanent Residence
The owner must intend the property as a permanent residence. Florida law does not require a minimum number of days in the state each year. The test is intent, supported by objective evidence: a Florida driver’s license, voter registration, vehicle registration, tax return filing address, and local professional relationships such as doctors and accountants. A person can maintain a second home elsewhere as long as Florida remains the primary residence. Filing a Declaration of Domicile with the clerk of court provides supporting evidence but is not required.
2. Actual Occupancy
The owner must actually live there. Temporary absences for travel, seasonal stays, school, military service, or medical treatment do not defeat the exemption as long as the owner intends to return. The Florida Supreme Court confirmed in Hillsborough Investment Co. v. Wilcox that a temporary absence does not forfeit the homestead when the owner intends to come back. Courts look at the facts of each case to decide whether occupancy and residency requirements have been met.
The property tax exemption also requires ownership and occupancy as a permanent residence, measured on January 1 of the tax year.
3. Ownership by an Individual
The property must be owned by an individual person. Title must be in the name of a natural person, not an LLC, corporation, irrevocable trust, or partnership. Transferring a primary residence into an LLC for liability protection strips the property of constitutional homestead protection entirely. An LLC may be appropriate for investment and rental properties, but it should never hold the owner’s home.
A revocable living trust can hold a homestead without losing the protection, but the trust must contain specific language giving the beneficiary a right to possess and occupy the property. Many older Florida trusts and trusts drafted in other states lack this provision. Florida land trusts also preserve homestead status by statute. Both structures require specific language and documentation to maintain the exemption.
Homestead and Marriage
A married person can maintain a homestead even when the spouse is not on the deed. The non-owner spouse holds a separate homestead interest under the Florida Constitution, so both spouses must sign off on any sale or mortgage of the property. Spousal consent requirements apply even when only one spouse holds title.
Married couples who own the homestead together typically hold title as tenants by the entireties, which adds a second layer of protection when only one spouse faces a creditor claim. In certain circumstances, separated spouses living apart can each claim a separate homestead if they maintain genuinely independent households.
Acreage Limits
Florida law places no cap on the dollar value of a protected homestead or the square footage of the home itself. The only size restriction applies to the land. Inside a municipality, the homestead may not exceed one-half acre of contiguous land. Outside a municipality, the limit is 160 acres.
If the lot exceeds the applicable limit, Florida Statute § 222.02 lets the owner designate which portion is the homestead, leaving the rest open to sale. The designation fails when the remainder cannot lawfully or practically be sold on its own. In Englander v. Mills, 95 F.3d 1028 (11th Cir. 1996), the Eleventh Circuit affirmed rejection of a designation that kept the lake frontage and road access and left a landlocked remainder, on a Winter Park lot that zoning made indivisible.
A couple living on a one-acre lot in Tampa can survey off the half acre containing the house only if the remaining half acre could lawfully be conveyed by itself. Where zoning makes the lot indivisible, the court orders the whole parcel sold and apportions the proceeds. Taxes and assessments come off the gross first, along with any mortgage given for purchase, improvement, or repair. The owners keep their acreage percentage of what is left.
Adjacent parcels count toward the homestead even when they carry separate legal descriptions and tax identification numbers. Buying the lot next door in the owner’s own name merges it into the homestead. If the combined land exceeds half an acre inside a city, the purchase forfeits protection on the excess.
We hear the acreage question from owners of valuable in-city homesteads, usually after the neighboring lot comes up for sale. Titling the adjoining lot in an LLC keeps it from merging into the homestead, because land owned by an entity cannot be homestead property.
Properties with multiple structures on one parcel, such as guest houses or detached buildings, may qualify as a single homestead if the structures sit on contiguous land and are used as part of the residence. Acreage disputes involve a size and boundaries analysis.
Deadlines
The property tax exemption has two dates. The owner must own and occupy the home as a permanent residence on January 1 of the tax year. The application should reach the county property appraiser by March 1. Missing March 1 does not always mean losing the exemption for the year. Florida law permits late applications until shortly after the county mails its Notice of Proposed Property Taxes (the TRIM notice) in August, although late filers may need to petition the county’s value adjustment board.
The creditor protection has no minimum ownership or residency period. The exemption attaches the moment the owner occupies the property with the intent to make it a permanent residence.
A person who purchases a Florida home today, moves in today, and is sued tomorrow has full homestead protection. General civil judgments do not create a lien on homestead property even if the judgment is recorded in the county where the home is located.
Buying a Home When a Judgment Is Already Recorded
A recorded judgment does not prevent a debtor from buying a fully protected Florida homestead. Florida courts have held that when a debtor acquires title and occupies the home at the same time, the homestead protection takes priority and the pre-existing judgment lien does not attach.
The trap is owning the property before occupying it. A recorded judgment attaches to any non-homestead real property the debtor owns in a county where it is recorded. A vacant lot purchased for a future home, a house under construction, or an inherited house that sits empty is not yet homestead. The lien therefore attaches. Moving in later does not remove it. Narrow exceptions protect some homesteads during construction, but the general rule controls most cases.
For a debtor with a recorded judgment, the closing and the move-in should happen together. Buying a teardown or an unbuilt lot in a county where the judgment is recorded gives the creditor a lien that survives the later homestead.
Florida Designation of Homestead Form
A designation of homestead is a signed statement, recorded with the clerk of the circuit court, that describes a Florida property and declares it to be the owner’s homestead. Florida law makes recording it optional. The constitutional exemption attaches when the owner occupies the property as a permanent residence. An owner who records nothing forfeits nothing.
Florida Statute § 222.01(1) sets out what the statement contains. The person making the claim must live in Florida and must sign the statement. The statement must describe the real property, mobile home, or modular home being claimed and declare that the described property is that person’s homestead. Nothing in the statute requires an oath, a recorded judgment, or a contract to sell.
An instrument concerning real property may not be recorded in Florida unless the person who signed it acknowledged the signature or a subscribing witness proves it. A designation of homestead is therefore signed before a notary, even though § 222.01(1) asks only for a signature. Because the clerk of the circuit court is the county recorder, the statement goes into the same official records that hold the county’s deeds and mortgages.
A recorded designation puts a dated public claim on the property before any creditor moves. A judgment recorded by a general creditor does not attach to property that is already homestead, but it still shows up on a title search as a cloud on the title. Closing over that cloud takes the sworn notice of homestead under § 222.01(2), which starts a 45-day creditor deadline.
Once the sheriff has levied on the land, the owner may hand the levying officer a sworn designation under § 222.02, and only the remainder is then subject to sale.
| Document | When it is used | Where it goes | What it does |
|---|---|---|---|
| Designation of homestead (§ 222.01(1)) | Any time; no judgment and no levy required | Recorded with the clerk of the circuit court | Puts a signed, dated homestead claim on the public record |
| Notice of homestead (§ 222.01(2)) | A certified copy of a judgment is recorded and the owner has a contract to sell or a mortgage commitment | Recorded in the county’s public records; the clerk mails it to the judgment creditor | The creditor has 45 days to sue, or a buyer or lender closing within 180 days takes free of the judgment lien |
| Notice designating homestead after levy (§ 222.02) | A levy has already been made on the land | Sworn and delivered to the officer who made the levy, before the sale day | Only the remainder of the levied land is subject to sale |
Download this form: Word (.docx) | PDF · Part of our asset protection forms library.
Sale Proceeds
Proceeds from selling a homestead remain protected if the owner intends to reinvest them in a replacement Florida homestead within a reasonable time. Courts evaluate reasonableness based on the facts of each case. A few months to two years has been found reasonable in some cases, while four years or longer has been found too long in others.
To preserve the protection, the owner should deposit the proceeds into a homestead account, a new and separate account that holds only the sale proceeds. Commingled proceeds lose the exemption. Courts treat mortgage refinance proceeds differently from sale proceeds. Moving homestead proceeds into other exempt assets instead of a replacement home has been attacked as a fraudulent transfer in some cases.
Application Process
The tax exemption requires an application with the property appraiser in the county where the home is located. Required documents typically include a Florida driver’s license, the recorded deed or tax bill, vehicle registration, and Social Security numbers for all owners and their spouses.
Once granted, the exemption renews automatically each year as long as ownership and use of the property do not change. Any change in title, including recording a new deed or transferring the home into a trust, requires a new application.
A home held in a revocable trust can still qualify for the tax exemption, but some counties require the trust to include language giving the beneficiary the right to occupy the property. In some counties, a full copy of the trust agreement must be provided.
Exceptions to Homestead Protection
The constitutional protection of the Florida homestead has a short list of exceptions. Three appear in the state constitution itself, so the legislature cannot add to them, and courts cannot create new ones. The recognized exceptions are:
- Purchase money mortgages and other liens the homeowner voluntarily agrees to
- Property taxes and government assessments
- Mechanics’ liens for labor and materials used to improve the property
- Condominium or homeowners association assessment liens, which Florida courts enforce as voluntary obligations under the association’s governing documents even though the constitution does not list them
Federal tax liens also override the state constitutional protection under federal supremacy principles, though the IRS follows internal policies that make forced sales of a primary residence rare in practice. Outside these categories, no other lien can attach to homestead property, including judgments for fraud, negligence, or breach of contract.
Bankruptcy
Federal bankruptcy law imposes its own restrictions on Florida’s homestead protection. Under § 522(p), an owner is capped at roughly $214,000 for whatever homestead interest was acquired inside the 1,215-day window before a bankruptcy filing. A mortgage paydown made in that window counts. Time owning a prior Florida homestead counts toward the 1,215 days when the sale proceeds rolled into the current home. Section 522(o) can reduce the exemption when a debtor moved unprotected assets into homestead equity within 10 years before filing, intending to hinder, delay, or defraud a creditor.
These federal limits apply only in bankruptcy. An owner who converts assets into a homestead and never files bankruptcy receives the full state constitutional protection under Havoco.
The 1,215-day rule falls hardest on new Florida residents. A homeowner who bought the Florida home less than 40 months before filing bankruptcy keeps roughly $214,000 of protected equity, whatever the home is worth. Florida’s unlimited exemption does not apply until the 40 months have run.
Claiming the homestead exemption also has a cost inside bankruptcy. A Florida debtor who claims homestead protection keeps only the $1,000 constitutional personal property exemption. A debtor who does not own a home, or who does not claim the homestead, adds a $4,000 wildcard exemption. The two stack, so that debtor protects $5,000.
Money From Fraud or Theft
Money obtained through fraud, theft, or breach of fiduciary duty cannot be converted into homestead protection. A creditor who can trace specific funds from the wrongdoing into the property can seek a court-ordered equitable lien on the traceable amount. A homestead bought with lawfully earned money remains exempt even when the judgment against the owner is based on fraud.
Other Situations That Affect Homestead Protection
Homestead protection depends on continued use as a primary residence and individual ownership. Several common situations test that status without necessarily defeating it.
Renting out the homestead. An owner who rents out part or all of the homestead does not automatically lose creditor protection. The answer depends on whether the owner continues to use the property as a primary residence. The abandonment standard for creditor protection differs from the property tax 30-day rule.
Running a business from the homestead. Florida case law allows a business operated from the homestead without defeating the exemption, provided the residential use remains primary.
Non-citizen owners. Legal permanent residents and, in some circumstances, non-citizens without legal immigration status can qualify for homestead protection. The Florida Supreme Court denied the exemption in Cooke v. Uransky to a Canadian citizen here as a tourist, where neither he nor his family had a legal right to reside permanently. The Court twice confined that result to the case’s own facts. Florida’s Third District has since held that the homesteader’s own intent decides the question. The bankruptcy courts have not settled it.
Moving to a nursing home. For an owner who relocates to a nursing home, abandonment turns on whether the move is temporary or permanent. The move also raises Medicaid eligibility and estate recovery questions.
Waivers and contract provisions. Homestead protection can be waived through a mortgage but not through general contract provisions.
Divorce. A divorce can alter the exemption through equitable distribution.
Co-Ownership With a Non-Resident
When a homestead is co-owned with someone who does not live in the property, only the resident owner’s share is protected. Parents sometimes add an adult child to the deed so the home passes to the child automatically at death. If the child lives elsewhere, a judgment against the child becomes a lien on the child’s interest, and the child’s creditor can force a judicial sale of the entire property. The parents would receive their protected share of the proceeds and lose the house.
This risk applies to any co-ownership arrangement where one owner does not occupy the property as a permanent residence. The safest approach is keeping title solely under the resident owner, or for married couples, as tenants by the entireties.
FAQs
Do I have to file anything to get creditor protection? No. The creditor protection is automatic the moment the owner occupies the property as a permanent residence. No application, filing, or waiting period is required. The homestead tax exemption is a separate benefit that does require an application with the county property appraiser, but failing to apply for the tax benefit does not affect creditor protection.
How long do you have to live in a home to get homestead protection? There is no minimum period. Protection begins the day the owner occupies the home intending to make it a permanent residence. A homeowner sued the day after moving in has the same protection as one who has lived there thirty years.
Can a creditor put a lien on my homestead? A general judgment creditor cannot place an enforceable lien on homestead property, even if the judgment is recorded in the county. Only a narrow set of lien types can attach to a homestead: mortgages, property taxes, mechanics’ liens, HOA assessments, and federal tax liens.
What happens if I put my house in an LLC? The homestead loses its constitutional creditor protection. The exemption requires ownership by a natural person. Transferring a primary residence into an LLC or corporation strips the protection entirely. An irrevocable trust generally forfeits homestead protection as well.
A revocable living trust can hold a homestead if the trust contains specific language giving the beneficiary a right to occupy the property, but an LLC should never hold the owner’s home.
Can I own a second home in another state and still claim Florida homestead? Yes. Florida does not prohibit owning property in other states, but the Florida property must be the owner’s permanent, primary residence. Owning a vacation home or investment property elsewhere does not disqualify the Florida home, as long as the owner genuinely lives in Florida as a permanent home. A homeowner cannot claim Florida’s homestead tax exemption while also claiming a residency-based tax exemption on property in another state.
Does the creditor protection continue after I die? The creditor exemption survives. The homestead is not part of the probate estate and cannot be sold to pay the deceased owner’s debts. Who receives the home is decided by Florida’s homestead inheritance rules, which are separate from the creditor protection. The property tax benefits may or may not transfer depending on whether the heir qualifies as a surviving spouse or other eligible occupant.
Can I lose homestead protection while still living in the house? As long as the owner continues to live in the property as a permanent residence and holds title as an individual, protection continues. The most common ways to lose protection are transferring title to an entity like an LLC, permanently moving elsewhere, or adding a co-owner who does not live there (which exposes the non-resident’s share to creditors).
How much is the Florida homestead exemption worth on property taxes? The exemption removes $25,000 of assessed value from all property taxes. A second, inflation-indexed exemption removes another $26,411 of assessed value above $50,000 from non-school taxes in 2026. The combined exemption is $51,411 for 2026; the dollar saving is that value times the local millage rate, so it differs by county. The Save Our Homes cap that comes with the exemption usually saves far more over time.
What is the deadline to file for the homestead tax exemption? The application should reach the county property appraiser by March 1. On January 1 the home must be the permanent residence of either the owner or the owner’s legal or natural dependent. Late applications are accepted until shortly after the TRIM notice mails in August, though late filers may need to petition the value adjustment board.
Do I have to reapply for the tax exemption every year? No. The exemption renews automatically as long as ownership and use do not change. Any title change requires a new application by the following March 1.
What happens to my property taxes when I inherit a homestead? The Save Our Homes assessment cap resets when the property changes ownership, so an heir is assessed at the home’s current market value and the tax bill can jump sharply. A surviving spouse who keeps living in the home and files for the exemption keeps the cap. So does an heir the owner supported as a legal or natural dependent, if that heir was a Florida permanent resident. Everyone else starts over.
Can a married couple claim two homestead exemptions? Generally no. Florida allows one homestead exemption per family unit, so a married couple living together gets one exemption even if each spouse owns a separate property. The narrow exception covers genuinely separated spouses. Courts and property appraisers have allowed two exemptions where the spouses maintain separate permanent residences and separate financial lives, though appraisers examine those claims closely.
The two-exemption problem also arises by drift. A couple moves to Florida, claims the new homestead, and leaves the old state’s principal-residence exemption running on the house they kept. Property appraisers cross-check other states’ exemption rolls. An improper exemption triggers a lien for up to ten years of back taxes plus a 50% penalty and 15% annual interest.