
Offshore Bank Accounts

An offshore bank account holds funds at a bank outside the United States. It protects assets only when that bank has no U.S. presence. Americans open offshore accounts for asset protection, currency diversification, and international business. Offshore accounts are legal and fully reportable to the IRS. They do not reduce U.S. taxes.
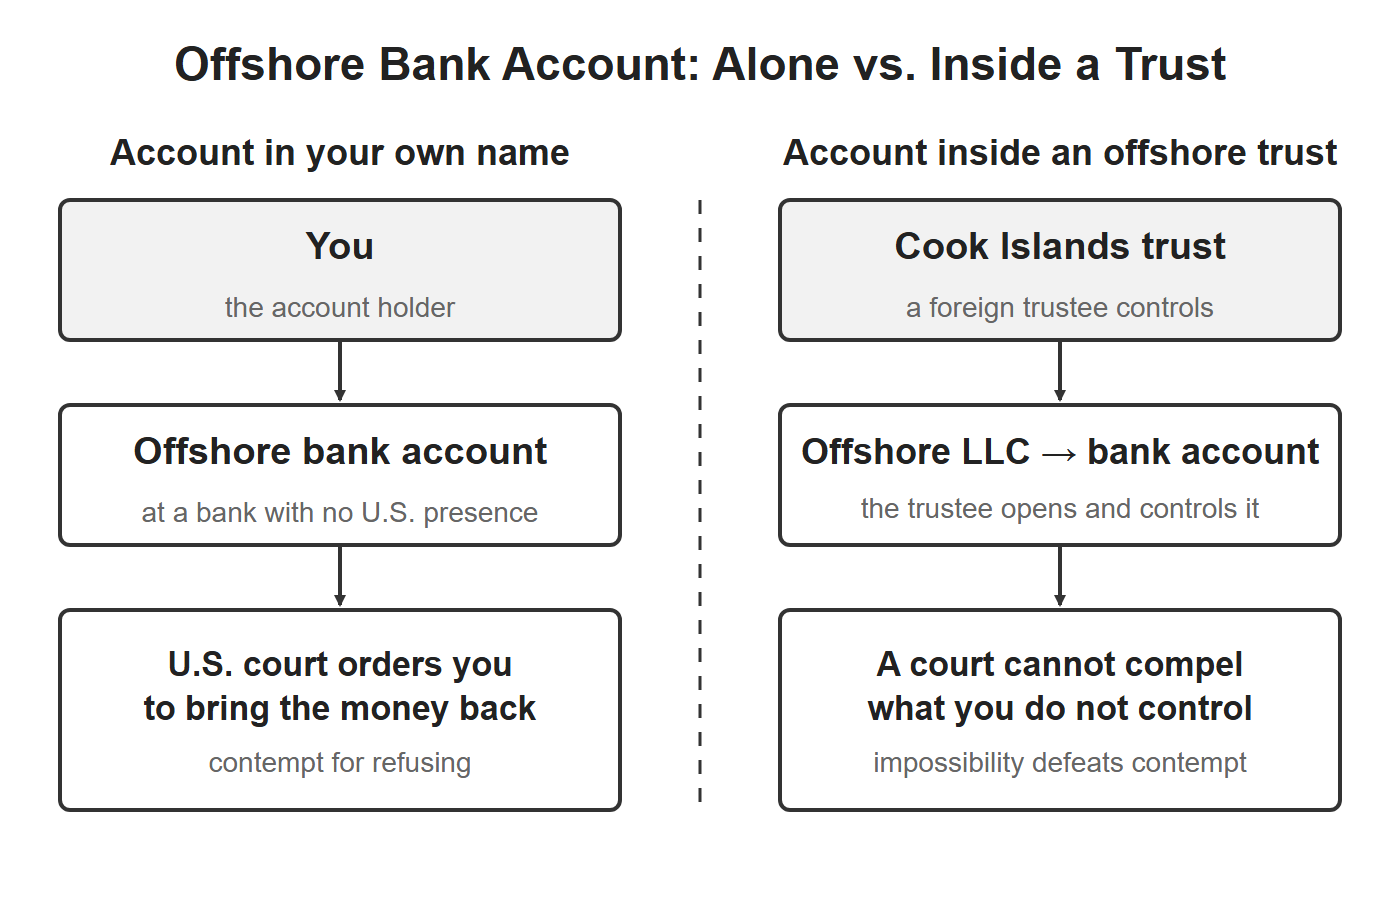
An offshore account alone does not fully protect assets from creditors. A U.S. court can order the account holder to repatriate the money. Someone who holds an offshore account in their own name can be held in contempt for refusing. Full protection requires pairing the account with an offshore trust that removes the individual’s legal control over the funds.
What Makes a Bank Account Offshore
An account is offshore for asset protection purposes only when the bank holding it has no U.S. presence (no branches, subsidiaries, or affiliates inside the United States). A bank with U.S. offices can be served with process at its domestic office. A court with jurisdiction over the bank can then order it to surrender accounts held abroad. But not every state lets a garnishment served on the U.S. branch reach deposits at the bank’s foreign branches. A bank with no U.S. footprint has no obligation to comply with a U.S. court order.
Correspondent accounts are a separate question. Every bank that clears dollars keeps one at a U.S. bank, so a correspondent relationship is not by itself a U.S. presence. Still, a New York court can reach a foreign bank on claims arising out of its own deliberate use of a New York correspondent account.
FDIC coverage is a reliable one-way test. If a bank’s accounts are covered by FDIC insurance, the bank has a U.S. presence. That is because an insured deposit is by statutory definition held at a U.S. institution or an insured U.S. branch and payable in the United States.
The reverse does not follow. A foreign bank’s U.S. branch or agency is almost always uninsured, so the absence of FDIC coverage proves nothing about U.S. presence. Since December 19, 1991, a foreign bank has needed an insured U.S. subsidiary to take ordinary retail deposits. An FDIC-insured account at a foreign bank’s U.S. branch is not an offshore account for asset protection purposes, regardless of where the parent institution is headquartered.
Day to day, an overseas bank account functions like a domestic account with two differences. It can hold multiple currencies, and it sits outside U.S. court jurisdiction. Opening an offshore account runs through a bank compliance review that averages about three weeks. Funding usually arrives by international wire.
Speak With Our Attorneys
Jon and Gideon Alper set up offshore trusts for clients nationwide. Consultations are free and confidential, by phone or Zoom, and usually available within one business day. You’ll speak directly with Jon or Gideon.
Request a Free Consultation
Can Creditors Seize an Offshore Bank Account?
Creditors cannot garnish an offshore account held at a foreign bank with no U.S. presence, but a U.S. court can order the account holder personally to bring the money back. No state or federal court can compel a bank it cannot reach to freeze the account or surrender its funds, so the realistic collection path runs through the account holder.
Reaching the money at the bank itself requires domesticating the U.S. judgment abroad, retaining local counsel, and pursuing collection under the foreign country’s rules. The Cook Islands does not recognize U.S. judgments against trust property, so the creditor must file an entirely new lawsuit there. Switzerland and Singapore will hear a recognition proceeding, which costs the creditor time and local counsel and gives the foreign court its own review.
The creditor has a simpler alternative: ask a U.S. court to order the account holder personally to repatriate the funds. If the individual holds the account in their own name, the court can compel them to wire the money back and hold them in contempt for refusing.
Courts have exercised this power repeatedly. In FTC v. Affordable Media, the settlors who controlled a Cook Islands trust were held in civil contempt and taken into custody when they failed to repatriate the trust’s assets. In the In re Lawrence case, the Eleventh Circuit affirmed a contempt order that jailed a settlor and fined him $10,000 a day for refusing to turn over trust assets. The contempt remedy is the central vulnerability of any offshore account held without a trust or LLC structure.
Federal agencies such as the FTC and SEC present a separate risk. In an enforcement action, an agency can obtain a freeze order without advance notice the same day it files suit, and the order binds the defendant personally no matter where the assets sit. Spending from an offshore account in defiance of that order is contempt.
The order still has a limit. An injunction binds only the parties, their agents, and those acting in concert with them, so a foreign bank or trustee that is not a party to the case is outside its reach. Trust structures with an independent foreign trustee rely on that limit.
Most creditors do not pursue foreign litigation unless the judgment is large. The cost, delay, and uncertainty of offshore collection make it uneconomical for typical civil judgments. That imbalance gives the account holder bargaining power in settlement negotiations even without a trust.
Are Offshore Bank Accounts Legal?
Offshore bank accounts are legal for U.S. citizens and residents. No law prohibits Americans from holding financial accounts at banks outside the United States. Roughly 1.5 million Americans maintain foreign accounts for international business, currency diversification, investment management, and asset protection.
Using an offshore account to evade taxes, conceal income, or launder money is illegal. The distinction turns on disclosure. An offshore account reported on the FBAR, Form 8938, and the taxpayer’s income tax return complies with U.S. law. An account that is not reported exposes the holder to civil penalties and to criminal prosecution, which carries potential imprisonment.
Concealment is what makes an offshore account illegal; a fully disclosed account is lawful no matter which country the bank sits in.
FATCA ended offshore banking secrecy for U.S. persons after its enactment in 2010. More than 110 countries and over 300,000 foreign financial institutions now report U.S. account holder information directly to the U.S. government. Foreign banks that fail to comply face a 30% withholding tax on their U.S.-source income. The IRS has independent access to information about U.S.-held offshore accounts regardless of whether the taxpayer files the required disclosures.
Tax compliance strengthens asset protection. A fully reported offshore structure removes tax noncompliance as a vulnerability that a creditor or government agency could exploit. The protection itself comes from keeping the assets outside U.S. court jurisdiction.
How to Open an Offshore Bank Account (and Why Applications Stall)
Most offshore banks that accept U.S. account holders require the account to be opened through a foreign legal entity, typically an offshore LLC or trust, rather than in the individual’s personal name. Opening runs through five stages: bank selection, a documented application, the bank’s compliance review, approval, and an initial funding wire. The bank’s due diligence controls the pace.
Minimum deposit requirements vary by bank and jurisdiction. Most banks used in asset protection planning require initial deposits of $100,000 to $500,000. Since FATCA, some foreign banks have stopped accepting U.S. account holders because the compliance costs exceed the revenue from serving Americans.
See What a Cook Islands Trust Costs
Our legal fee for a Cook Islands trust is $15,000. Consultations are free and confidential, by phone or Zoom, and you’ll speak directly with the attorney.
See Pricing & Request a Consultation
Three recurring problems unrelated to the legal structure stall offshore bank account openings: missing source-of-funds documentation, a poor match between the applicant’s profile and the bank’s book, and a bank’s withdrawal from U.S. business between inquiry and application.
The documentation requirement surprises most U.S. applicants. A compliance officer in a well-regulated jurisdiction expects more than current bank statements. The bank wants the paper trail back to how the money was earned: sale documents for a business exit, prior years’ tax returns for accumulated wages, inheritance papers, settlement agreements, or closing statements from a real estate sale. An applicant who assumed domestic banking history would be enough finds the bank holding the application open while it requests older records.
A bank that accepts U.S. persons on paper may still decline an applicant whose situation does not fit its book. Some Swiss private banks require at least $1 million in liquid assets and prefer a wealth management relationship. Singapore banks accepting smaller balances often require an established business connection to the region.
Foreign banks also tighten and loosen their U.S.-persons policies over time. A bank that accepted U.S. applicants when first contacted may have closed that channel by the time the application is ready. One that paused U.S. business may later reopen for specific account types. A bank’s current policy has to be confirmed at application time.
Offshore Banking Jurisdictions
Switzerland, Singapore, and the Channel Islands (Jersey and Guernsey) are the most common banking jurisdictions for U.S. persons seeking asset protection. The jurisdiction where the bank account is located does not need to match the jurisdiction where the trust or LLC is formed. A Cook Islands trust or a Nevis LLC can hold its accounts at a bank in Switzerland or Singapore.
Picking a banking jurisdiction is a banking decision. The trust jurisdiction provides the legal protection. The bank’s jurisdiction has to fit the asset profile and the intended use of the account. Treating the choice as a privacy or tax decision, or picking on reputation alone, causes much of the trouble that stalls applications.
Switzerland fits larger balances and a wealth-management orientation. Swiss banking has higher minimum balances and fees, with a long history of political stability and capital preservation.
Singapore suits Asia-facing diversification and active trading. Singapore banks operate under strong regulatory oversight and have become a common alternative for account holders who want distance from both the U.S. and European financial systems.
The Channel Islands are a sterling and expatriate banking center. Jersey enforces a U.S. money judgment only through a fresh action in its own courts. Its depositor compensation scheme does not cover accounts owned by companies or trusts.
Nevis and the Cook Islands, the trust jurisdictions themselves (Nevis in the Caribbean, the Cook Islands in the South Pacific), offer an account in the same place as the trust but few practical banking options. Banks there tend to be smaller, with fewer investment services. Cook Islands trustees routinely place trust accounts in New Zealand, Singapore, or Switzerland instead.
A bank that works for asset protection has no U.S. branches or subsidiaries, sits under strong regulatory oversight in a politically stable country, and accepts U.S. persons through foreign entities. Banks that meet these criteria exist across multiple continents.
Offshore Bank Accounts and Offshore Trusts
An offshore bank account and an offshore trust address different risks. The bank account moves money outside U.S. court jurisdiction so a creditor cannot garnish it through domestic process. The trust removes the individual’s legal control over the money so a court cannot compel them to bring it back.
The most common offshore asset protection structure places the bank account inside an offshore LLC, which is owned by a Cook Islands trust. The foreign trustee controls the account under the trust agreement. When a court orders repatriation, impossibility is a defense to contempt, but only when the settlor genuinely lacks control over the funds. The defense failed in both Affordable Media and Lawrence because the settlors kept control of their trusts. Lawrence holds that a settlor responsible for his own inability to comply cannot claim impossibility.
Under the trust-LLC structure, the foreign trustee opens and controls the LLC bank account. Once the structure is fully active, the settlor cannot wire funds out independently, and the trustee is a counterparty to every later transaction.
Neither the account nor the trust works as well alone. Offshore asset protection combines both so that a creditor’s domestic remedies do not reach the funds and the settlor holds no control a court can compel.
For individuals whose assets do not justify the cost of a full trust structure, a Nevis LLC holding an offshore account is a mid-range alternative. The LLC’s charging order protections add a layer beyond what a personally held account provides, though not as strong as a trust-owned structure. A Nevis charging order expires after three years and cannot be renewed. Creditors must also post a bond in an amount set by the Nevis High Court before filing suit against a member’s interest.
Tax Reporting for Offshore Accounts
Offshore bank accounts carry reporting obligations whose penalties can exceed the account balance. The filings that keep an offshore account legal are the FBAR, IRS Form 8938, and the foreign-account question on Schedule B of the tax return. The FBAR (FinCEN Form 114) is due when combined foreign accounts exceed $10,000 at any point in the year. Form 8938 applies once foreign financial assets cross $50,000 at year-end or $75,000 at any time for single filers; the joint-filer thresholds are $100,000 and $150,000.
When the account is held through a foreign trust, the trust’s U.S. grantor also files Form 3520 annually and is answerable for the foreign trustee’s Form 3520-A, the trust’s own return. A foreign LLC treated as a disregarded entity adds Form 8858. These filings are informational. The grantor’s CPA prepares them, and the foreign trustee signs the 3520-A and files it with the IRS. The attorney structures the trust and LLC, and the accountant handles the annual reporting.
Costs of Offshore Banking
Offshore bank account costs include the bank’s own fees and the professional fees for tax compliance. Most offshore institutions charge an annual maintenance fee of $500 to $2,500 depending on the bank and account type, and wire transfers run $25 to $75 each. Some banks also charge custody fees on securities, calculated as a percentage of assets under custody.
The larger ongoing expense is tax compliance. When a foreign trust holds the account, CPAs experienced in foreign trust reporting charge $2,000 to $3,000 per year, billed separately from ordinary tax preparation.
The initial cost depends on whether the individual is opening a standalone account or adding one to an existing offshore structure. For individuals who already have an offshore trust or LLC in place, the trustee handles the account opening and the incremental cost is modest.
A new Cook Islands trust alone adds about $21,000 in setup costs and about $5,000 in annual trustee fees. When the trust holds the account through an LLC, the totals are about $26,000 to establish and about $6,000 per year. Forming a standalone Nevis LLC typically costs $3,000 to $5,000 in legal fees, plus government filing and registered agent costs.
Offshore banking is most cost-effective for individuals with liquid assets exceeding $250,000 who face a risk of being sued. A full trust structure typically makes sense at $1 million in total assets or $500,000 in liquidity. Below the banking threshold, account fees, compliance costs, and entity maintenance can eat a large share of the money being protected. Domestic strategies including exemptions, tenancy by the entirety, and LLC structuring may provide adequate protection at lower cost.
Is an Offshore Bank Account Worth It for Asset Protection?
An offshore bank account is worth the cost for individuals with more than $250,000 in liquid assets who face a risk of being sued. The account keeps the money where a creditor’s garnishment cannot reach it; a U.S. court can still order the account holder to bring it back.
Offshore bank accounts are not suited to everyday transactional banking. Wire transfers between offshore and domestic accounts can take several business days. Most offshore banks do not issue U.S.-compatible debit cards, checks, or ACH-connected accounts, so accessing funds requires advance planning.
Offshore accounts offer weaker protection in bankruptcy than in state court collection. A debtor who files for bankruptcy must disclose all assets, including offshore accounts, and the bankruptcy trustee has broad authority to compel turnover. A properly structured offshore trust still creates enforcement barriers that domestic structures cannot match in bankruptcy, but the protections are not as strong as in state court proceedings.
A Cook Islands trust holding the account through an offshore LLC completes the protection. Control of the funds moves from the account holder to the foreign trustee. The full structure justifies its cost at $1 million in total assets or $500,000 in liquidity.
Alper Law has structured offshore and domestic asset protection plans since 1991. Schedule a consultation or call (407) 444-0404.
